Independent perspectives on data center development, power, investment and AI infrastructure
France’s data centre opportunity will be delivered through land agreements, grid connections, permits and customers. Here is what to test at Data Centre World Paris 2026 before committing capital.
A deliverable 40 MW IT phase can be a stronger investment than a speculative gigawatt campus. Matthieu Gallego argues that valuations and acquisition payments should follow verified power, customer and commissioning milestones.
AI growth does not guarantee the value of every project. Matthieu Gallego examines secured power, delivery timelines and qualified demand, supported by PowerlandMap intelligence and external sources.
A site, 100 MW and delivery in 2028 are not enough to qualify a project. Here is how I bring together IT capacity, CAPEX, grid connection and customer requirements to understand what can actually be delivered.
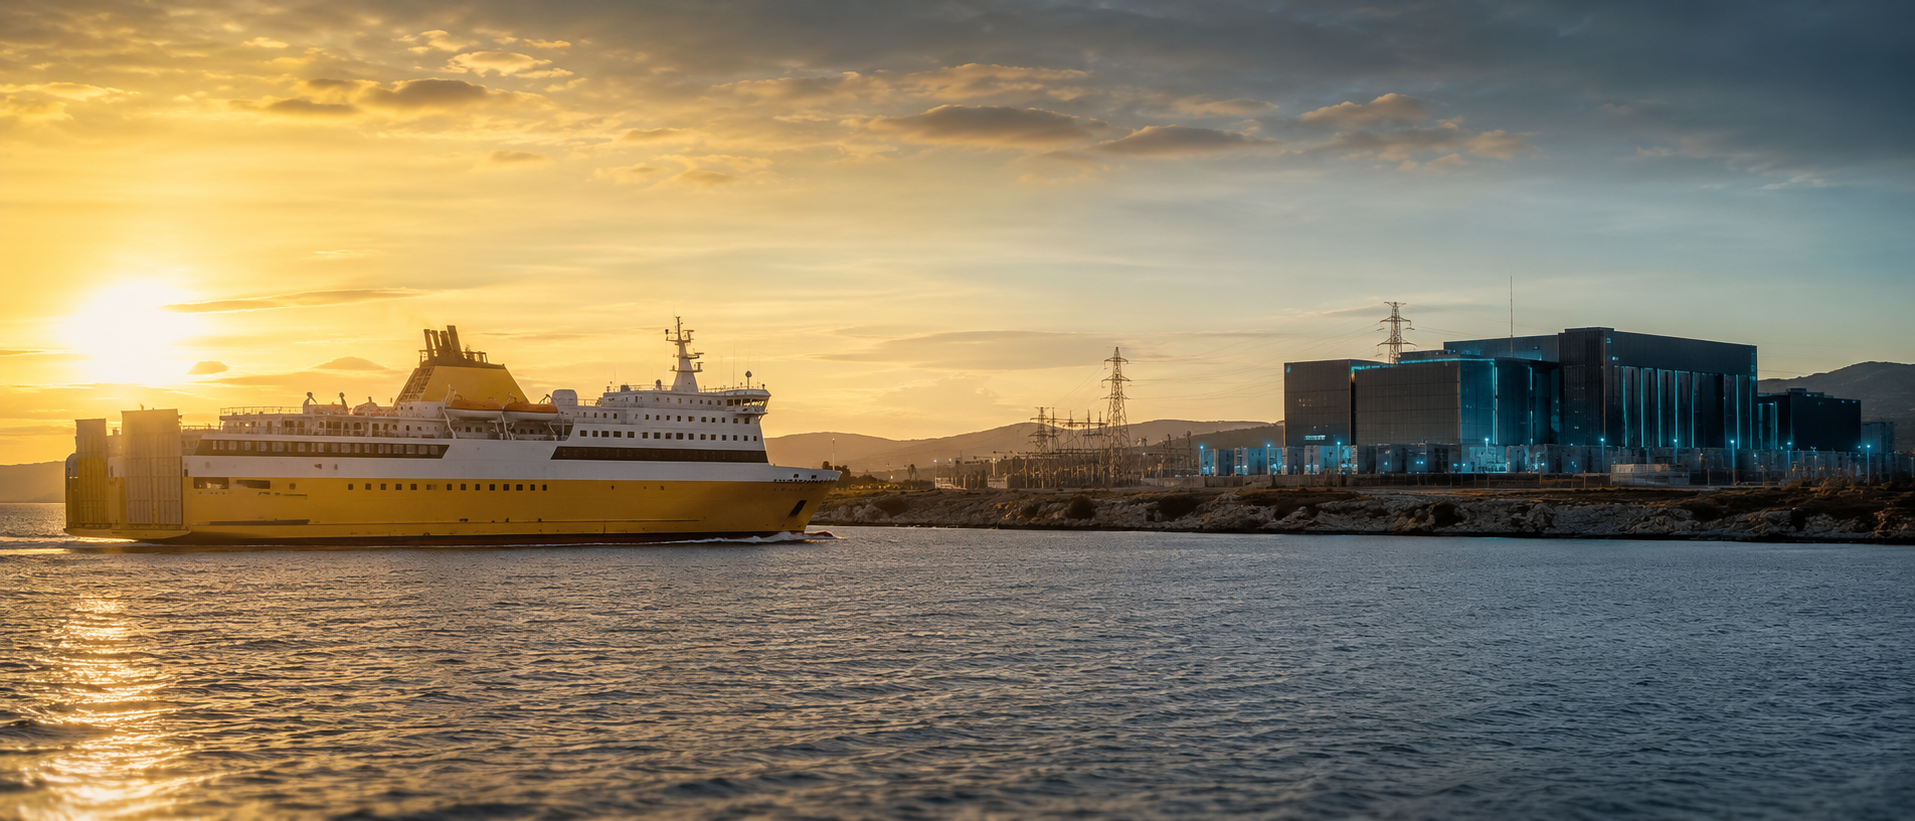
Depuis la plage, un ferry semble écraser le paysage. Mais face à un data center de 20 MW IT, lequel pèse réellement le plus lourd en construction, en exploitation et sur son environnement ?
AI infrastructure is becoming easier to finance when power, customer contracts, tenant credit and technical delivery stand up to scrutiny. Bankability remains the differentiator.
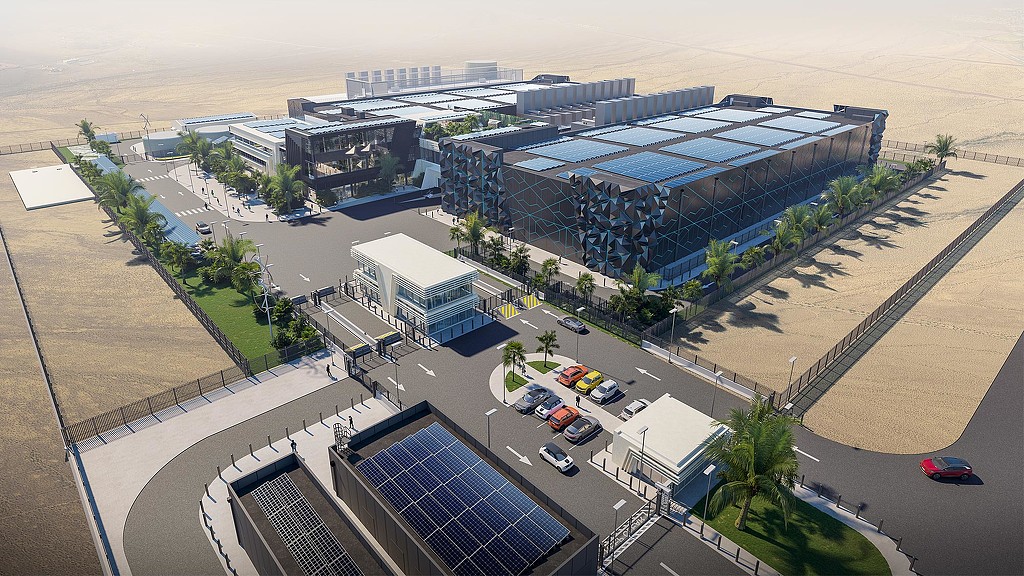
France, Poland and the UAE require different development sequences. Power, permits, phasing and customer demand determine the right approach for each project.
Grid capacity, not construction capacity, now sets the pace of data center delivery in Europe. Powered land has become the binding constraint of the AI build-out.
Rack densities moving from 10 kW to 130 kW change site selection, cooling strategy and the economics of every powered land position in the pipeline.